
Praseodymium Prices
Current Praseodymium price: $179.59 per kg.
Price as of Oct 09 2026. 1 The price shown above is the retail price for private investors and is aligned with industry retail pricing. For bulk praseodymium purchases, whether for industrial use or investment, please contact us for a quotation.Praseodymium price performance over time
| Period | Praseodymium price then | Change to today |
|---|---|---|
| Current price | $179.59/kg | — |
| 1 year | $143.30/kg | +25.32% |
| 2 years | $110.00/kg | +63.26% |
| 3 years | $128.30/kg | +39.98% |
| 5 years | $151.40/kg | +18.62% |
| 10 years | $65.00/kg | +176.29% |
Praseodymium Historical Price Movement
Praseodymium prices are increasingly influenced by the expanding role of rare-earth magnet materials in electrification, advanced manufacturing, and clean-energy technologies.
At today’s price of $179.59 per kg,
praseodymium is
up 24.63% year to date,
up 86.88% since the start of 2025,
up 59.21% since the start of 2024,
and up 146.79% since the start of 2020,
when the praseodymium price stood at $72.77 per kg.
This reflects praseodymium’s role in permanent magnets, aircraft engines, specialised glass, and other high-performance applications, combined with a market where supply remains concentrated and vulnerable to refining bottlenecks.
Praseodymium annual price performance
| Current Praseodymium Price/kg |
2026 YTD | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 |
|---|---|---|---|---|---|---|---|
| $179.59 | 24.63% | 49.95% | -14.80% | -43.15% | -8.70% | 160.55% | 14.61% |
Praseodymium is a chemical element belonging to the rare earth group of metals. It has the atomic number 59 and is represented by the symbol Pr on the periodic table. Discovered in 1885 by Carl Auer von Welsbach, praseodymium has a silvery-white color when in its purest form.
To predict where praseodymium prices may head in the future (jump to forecast), it’s important to understand its many applications and who produces it. Let’s dive deeper into this valuable metal and what role it plays globally.
Praseodymium Uses
Praseodymium’s unique properties make it indispensable across various modern industries. For decades, it has been used as an alloying agent with softer metals such as aluminum and magnesium to strengthen them without reducing flexibility, particularly in aircraft engines and turbine components.
Its most important role today is in the production of neodymium–praseodymium (NdPr) permanent magnets, which are essential for electric vehicle motors, wind turbines, and precision electronics. These magnets are prized for their combination of strength, heat resistance, and low weight, all characteristics that have made them critical to the green energy transition.
Beyond magnets, praseodymium serves as a neutron absorber in nuclear reactors and plays a role in glass manufacturing, high-intensity lighting, and lasers. Certain praseodymium compounds emit vivid red and green light, making them valuable in TV and smartphone displays.
Praseodymium also continues to attract research interest in advanced fuel cells and medical applications, where its magnetic and radiological properties are being studied for targeted therapies such as Praseodymium-177, a beta-emitting isotope used in cancer treatment.
In short, praseodymium’s versatility, from clean energy and aerospace to medical and optical technologies, highlights why it remains one of the most strategically important rare earth elements for the decades ahead.
Where is Praseodymium Produced?
Praseodymium is not mined on its own. It occurs alongside other light rare earth elements, particularly neodymium, within bastnäsite and monazite ores. Globally, China remains the dominant producer, accounting for roughly 69% of rare earth ore output in 2024 and an even larger share once separation and refining are included. Outside China, the United States, Myanmar, and Australia contribute to global supply, although each operates at a far smaller scale.
China’s dominance extends well beyond mining. It controls more than 80% of the global rare earth processing capacity, making it a critical bottleneck in the entire supply chain. Even when other countries increase extraction, much of that material is still shipped to China for refining. As a result, the real supply concentration risk lies not only in mining but in the separation and processing stages, where China’s lead remains unmatched.
While China will remain the dominant force in the near term, several countries are beginning to develop alternative sources of praseodymium supply.
Emerging Producers
Outside China, a number of countries are working to expand or establish rare earth production, although most projects remain in early stages. Australia continues to scale output through companies like Lynas, while the United States and Canada are investing in domestic mining, separation, and magnet production to reduce their reliance on Chinese processing. Exploration and development efforts in Brazil, Vietnam, and Greenland have also accelerated, reflecting broader geopolitical interest in diversifying supply chains. These initiatives are promising, but they will take years to mature, meaning China is expected to remain the central supplier of separated praseodymium well into the next decade.
What Factors Determine the Price of Praseodymium?
Praseodymium prices are driven primarily by the balance between supply and demand. As a key component of high-performance NdPr permanent magnets, demand rises with the growth of electric vehicles, wind turbines, robotics, and advanced electronics. When these sectors accelerate, the pull on praseodymium intensifies, often pushing prices higher.
On the supply side, China remains the dominant force. It controls most of the global mining and more than 80 percent of the world’s processing capacity. Changes in China’s mining quotas, export controls, or environmental policies can quickly influence availability and cause sharp price movements. In recent years, reduced transparency around quota issuance and stricter reporting requirements have added to the uncertainty in the market.
Geopolitical developments also play a significant role. Decisions by Western producers to divert material away from China, disruptions in Myanmar’s ionic clay operations, or new critical-minerals policies in the U.S. and EU can all affect the flow of rare earth feedstock and ultimately influence global praseodymium pricing.
Understanding these supply-and-demand dynamics, especially China’s policy decisions and the pace of clean-energy technologies, is key to anticipating where praseodymium prices may move in the years ahead.
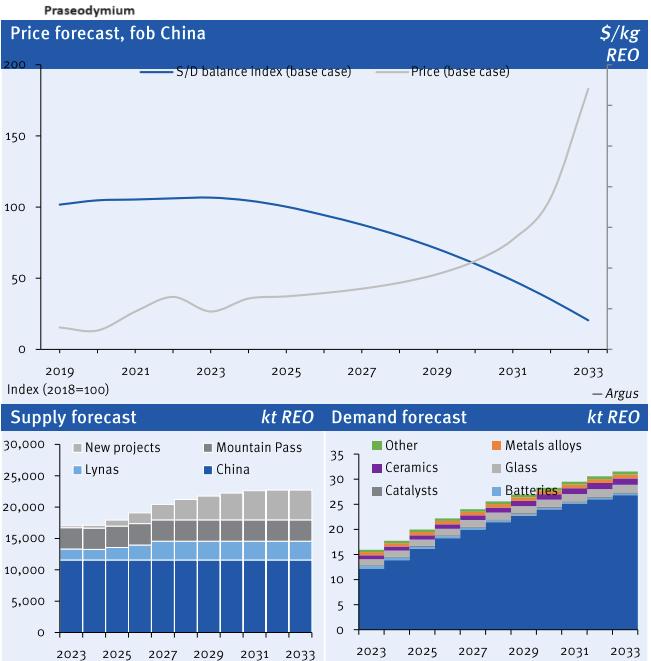
Praseodymium Price Forecast
Forecast last updated: .
At a glance
Praseodymium rebounded strongly in 2025, with SMI prices gaining 49.95%. The live table shows a further 24.63% rise in 2026 year-to-date and a displayed retail price of $179.59/kg on October 9. The underlying industry-partner quotation is dated October 5; currency conversions use the latest available ECB rate. The investment case rests on growing magnet demand, concentrated processing, and the practical difficulty of building dependable alternative supply chains. New production is advancing, but secure access remains commercially valuable.
What changed in 2026
1) Diversification is delivering real output.
MP Materials reported 840 tonnes of separated NdPr oxide production in the second quarter, up 41% year over year. These figures concern mixed neodymium-praseodymium material, not pure praseodymium. Magnet qualification is a further step beyond producing separated oxides.
2) China’s processing lead remains substantial.
The IEA’s July assessment puts China’s magnet-rare-earth refining share at 85% in 2025, down from over 90% in 2023. Diversification is progressing, but separation, metal-making, and qualified magnet production remain distinct bottlenecks. Announced capacity does not immediately become dependable industrial supply.
3) Trade relief still needs careful interpretation.
A September 28 official statement confirms the extension of the Kuala Lumpur trade arrangements to January 10, 2027. It does not explicitly confirm the position of individual rare-earth controls. Praseodymium was not among the seven elements named in China’s April 2025 controls, although restrictions elsewhere in the magnet supply chain can affect availability and sentiment.
4) The project pipeline is developing.
Lynas’ proposed acquisition of Meteoric would bring Brazil’s Caldeira project into its portfolio. The transaction remains subject to approvals, and project development must follow. It is a diversification opportunity, not immediate new separated-praseodymium supply.
What this means for praseodymium
The market is moving from a simple scarcity story toward a competition between demand growth and reliable supply delivery. Physical praseodymium retains strategic value because industrial users need material of the right quality, with a documented supply chain. The pace of diversification matters as much as the size of announced resources.
Price drivers tilting upward
- Steady end-use growth: EV powertrains and wind turbines remain structural sources of demand for NdPr magnets through 2030 and beyond. The IEA projects roughly one-third growth in magnet-rare-earth demand by 2030 under existing policies. This covers neodymium, praseodymium, dysprosium, and terbium collectively, rather than a standalone praseodymium forecast.
- Policy friction: Concentrated processing leaves buyers exposed to licensing changes and trade uncertainty. Precautionary inventory and efforts to secure alternative sources can support prices.
- Execution matters: Building mines is only part of the task. Separation expertise, consistent purity, downstream conversion, and customer qualification determine when new output becomes dependable supply.
Potential headwinds to watch
- Supply catch-up: Non-Chinese producers are adding units. If a synchronized ramp arrives into a softer macro patch, it could cap the upside for a few quarters. Easier trade flows could also reduce scarcity premiums.
- Technological substitution risk: Rare-earth-free motors and magnets, recycling, and material efficiency could moderate demand. Magnets that eliminate heavy rare earths can still use NdPr; they should not be confused with genuinely rare-earth-free alternatives.
6–12 month forecast view
- Bias: Moderately bullish.
- Rationale: SMI’s positive price performance, concentrated processing, and supply-chain uncertainty support the near-term case. If manufacturing activity and magnet orders hold, praseodymium should remain well supported. Stronger production or clearer trade relief could nevertheless trigger sharp pullbacks.
12–24 month forecast view
- Bias: Bullish with volatility.
- Rationale: Demand growth from EVs and wind remains supportive, while projects must progress from output to reliable industrial delivery. Operating producers are already expanding, so the balance will depend on actual ramp-up and demand.
3–5 year forecast view
- Bias: Bullish, with episodic volatility.
- Rationale: Magnet rare-earth demand growth is not a one-season story. Electrification supports the long-term pull on NdPr, while specialist processing remains difficult to replicate. Successful diversification, recycling, and substitution could reduce scarcity premiums, even as the metal’s strategic uses expand.
Why physical Praseodymium fits the Strategic Metals Invest playbook for savvy investors
- Praseodymium is a tangible, industry-grade material with useful industrial applications. Resale depends on buyer demand, specifications, transaction terms, and available liquidity.
- Supply concentration risk reinforces the value of verified purity, appropriate storage, and documented provenance.
- Magnet demand provides a structural investment rationale, while supply growth and changing technology require continued review.
How to Buy Praseodymium
Hobbyists interested in purchasing praseodymium may easily find it on sites like Amazon, Alibaba, and eBay. However, these sources offer no assurance of purity or liquidity for the buyer other than what another hobbyist is willing to pay.
For higher quality standards and greater certainty when buying this valuable rare earth metal, corporate buyers such as Samsung, Ford, Tesla, and Panasonic purchase through reputable metals dealers who serve as a bridge between high-tech industries seeking raw materials and the producers supplying them. Those that want to benefit from potential future price increases by owning some praseodymium can do so with us, knowing that they’re buying from the only licensed global industry supplier offering investors private access to this exciting asset class.
Praseodymium futures contracts are also traded in the Shanghai Metal Market (SMM).
How to Sell Praseodymium
Rare earths like praseodymium are highly sought-after by industry buyers like General Motors, LG, and Apple. However, they only purchase from reputable suppliers who can provide a full chain of custody, including analysis reports on purity levels plus adequate storage facilities.
Hence, to ensure the fast and safe liquidation of this resource for investors, it’s crucial that they source it from a reputable supplier, like ourselves, in the first place (all our praseodymium is certified min. 99% pure). Otherwise, they can only sell their praseodymium to hobbyists on online marketplaces like eBay or Alibaba.
Only industry metals traders have the bona fides required to sell to industry giants, guaranteeing market price sales.
1 This price is based on the latest available industry-partner price for Praseodymium, dated Oct 05 2026. Prices may be carried forward until a newer market price becomes available. Currency conversions use the latest available ECB exchange rate.
Calculations on this page last updated Oct 09 2026.