At a glance
- Price momentum: As of November 17, 2026, SMI’s price is $4,593.75 per kg. The page calculates a 131.61% gain in 2026, following a 42.03% increase in 2025.
- Outlook: Cautiously bullish while accessible supply remains constrained, with substantial correction risk after the rally.
- Strategic relevance: High-performance magnets connect terbium to electrification, defense, and advanced automation.
- Investor availability: New purchases remain paused through SMI’s supplier, underscoring the practical difficulty of accessing material.
What changed in 2026
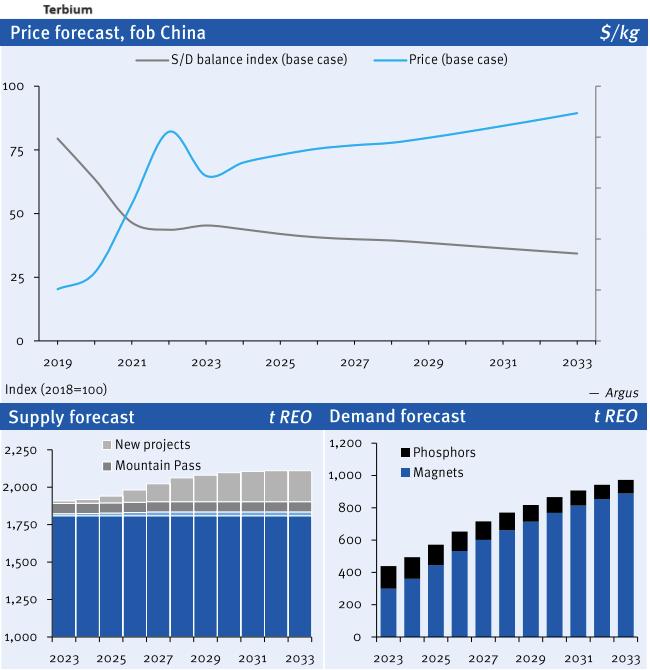
SMI’s published terbium price is now 228.95% above its level at the start of 2025. That advance highlights the value of access to physical material during supply tension, while making entry price and the risk of corrections more important.
On November 9, China extended the suspension of its October 2025 export-control expansion until January 10, 2027. This is distinct from the April 2025 licensing regime, which remains in place. The extension reduces the immediate risk of additional restrictions, but it does not remove existing licensing requirements or guarantee faster deliveries.
Alternative supply is making measurable progress. Lynas reported 23 tonnes of combined dysprosium and terbium oxide production in the September quarter, compared with 19 tonnes in the June quarter. This is a combined figure, not output of either metal alone. Planned maintenance at its Malaysian plant is expected to reduce December-quarter production, illustrating why actual deliveries matter more than a straight-line extrapolation of one quarter.
USA Rare Earth reported commercial-scale mixed rare earth carbonate shipments from Serra Verde beginning in October, with first sales and payments in November. The material contains dysprosium and terbium, but it is mixed feedstock, not individual separated oxide or finished metal. A 15-year offtake agreement covers all Phase I production. This is meaningful upstream diversification, not proof of freely available supply for every buyer; downstream separation, conversion, and customer qualification still matter.
Execution risk remains material elsewhere. REalloys’ November results update moved processing and separation trials with SRC from expected completion in 2026 into the first half of 2027, citing feedstock alignment and procurement lead times. Initial separated oxide production is expected in the second half of 2027, while its heavy-rare-earth metallization facility targets initial operations in the first half of 2028. The company says the trial delay does not change its broader plan. These are staged development targets, not present supply, and oxide production must not be confused with finished-metal availability.
What this means for Terbium
Terbium combines demanding industrial applications with difficult-to-diversify supply. It helps selected neodymium-iron-boron magnets resist demagnetisation at elevated temperatures, supporting compact, high-performance systems.
The opportunity extends beyond EVs and wind power into defense and advanced automation. AI-enabled robotics offers a further potential demand channel through motors and actuators, with terbium use depending on magnet design.
Separating heavy rare earths at customer-required purity involves specialist expertise, process control, and qualification. New plants take time to become dependable suppliers, although existing deliveries show that diversification is possible.
Key drivers of upward price pressure
- High-performance magnets: Selected EV motors, industrial drives, robotics, and wind-generation systems support demand. Terbium requirements vary by magnet grade and equipment design.
- Defense and strategic procurement: High-performance rare-earth magnets support demanding defense and aerospace systems; terbium use depends on the magnet grade and application. Efforts to secure dependable supply add a purchasing motive beyond ordinary commercial growth.
- Concentrated supply: Dependence on Chinese processing and Myanmar-linked feedstock leaves the market sensitive to licensing delays, border disruption, and geopolitical tension.
- Robotics and physical AI: Compact, high-performance motors and actuators offer another potential demand channel. Terbium consumption depends on the equipment deployed and the magnet grades selected.
Headwinds and downside risks
- Thrifting and substitution: Manufacturers are reducing heavy-rare-earth loading and developing suitable heavy-rare-earth-free magnets. These changes can weaken the link between motor sales and terbium consumption.
- New output: Lynas is producing, while further separation projects could expand supply. Announced capacity still needs commissioning, reliable feedstock, and customer qualification.
- The pace of supply growth: The IEA’s July 2026 outlook projects rising magnet-rare-earth demand alongside broadly sufficient aggregate mined supply under its main policy scenarios. This depends on projects progressing and does not establish a terbium-specific balance or guarantee accessible separated oxide. Growth in mixed feedstock alone cannot resolve separation and metal-refining bottlenecks, but successful downstream expansion could ease scarcity.
- Reversal risk: After a gain exceeding 130% this year, easier shipments, destocking, or weaker orders could trigger substantial price declines.
6–12 month outlook
Bias: Cautiously bullish, with high volatility.
Rationale: Limited accessible supply, licensing friction, and security-driven purchasing support prices. These pressures can persist even as new output emerges. The steep rally nevertheless leaves room for substantial corrections if shipments improve or buyers reduce inventories.
12–24 month outlook
Bias: Cautiously bullish, conditional on supply constraints.
Rationale: Industrial and defense purchasing can sustain pressure as alternative suppliers expand. The key test is whether additional separated oxide becomes dependable, customer-qualified supply quickly enough to ease competition for material. Faster deliveries or lower terbium use per magnet would weaken the bullish case.
3–5 year outlook
Bias: Constructive, with substantial uncertainty.
Rationale: Electrification, automation, robotics, and strategic supply security support terbium’s long-term relevance. AI-enabled robotics offers additional potential upside, depending on magnet design. The price outcome depends on how these uses develop alongside new supply, recycling, and more efficient magnet designs.
Why physical Terbium fits the Strategic Metals Invest playbook
Although new terbium purchases remain unavailable to private investors through SMI’s supplier, the reasons for following this market remain compelling:
- Specialised industrial value: Terbium helps selected magnets retain their strength at elevated temperatures, supporting compact systems where reliable performance matters.
- Several technology demand channels: EVs, wind power, industrial automation, and robotics broaden its relevance. AI-enabled robotics adds potential growth through motors and actuators, depending on design.
- Strategic defense relevance: Demanding military applications give dependable terbium supply significance beyond ordinary commercial demand.
- Concentrated and vulnerable supply: Chinese processing and Myanmar-linked feedstock expose the market to licensing, geopolitical tension, and disruption.
- Difficult diversification: Specialist separation expertise, consistent purity, and customer qualification take time to establish.
- Direct physical exposure: Suitable terbium oxide provides exposure to this specialised market without depending on the performance of an individual mining company.
For existing holders, these characteristics remain relevant while new purchases are paused. The medium- to long-term opportunity rests on industrial performance and access to constrained supply. Entry price, documented quality, storage, and resale terms still matter; scarcity cannot guarantee liquidity or returns.