
Rhenium Prices
Current Rhenium price: $7,409.21 per kg.
Price as of Oct 14 2026. 1 The price shown above is the retail price for private investors and is aligned with industry retail pricing. For bulk rhenium purchases, whether for industrial use or investment, please contact us for a quotation.Rhenium price performance over time
| Period | Rhenium price then | Change to today |
|---|---|---|
| Current price | $7,409.21/kg | — |
| 1 year | $4,211.60/kg | +75.92% |
| 2 years | $2,491.10/kg | +197.43% |
| 3 years | $1,902.10/kg | +289.53% |
| 5 years | $1,730.10/kg | +328.25% |
| 10 years | $2,299.23/kg | +222.25% |
Rhenium Historical Price Movement
Rhenium prices are increasingly shaped by the strategic importance of this exceptionally heat-resistant metal in aerospace and other high-performance industrial uses.
At today’s price of $7,409.21 per kg, rhenium is up 55.64% year to date, up 198.05% since the start of 2025, up 271.39% since the start of 2024, and up 332.91% since the start of 2020, when the rhenium price stood at $1,711.50 per kg.
This reflects rhenium’s importance in aircraft turbines, rocket-related applications, petrochemical catalysts, and other extreme-temperature environments, combined with a market where scarcity, by-product production, and limited substitution options can tighten supply quickly.
Rhenium annual price performance
| Current Rhenium Price/kg |
2026 YTD | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 |
|---|---|---|---|---|---|---|---|
| $7,409.21 | 55.64% | 91.50% | 24.61% | 24.18% | -7.14% | 23.14% | -17.91% |
Rhenium is an extremely rare and dense chemical element with atomic number 75, which makes it a part of the transitional metals group. It has a silver-grey appearance and melts at an incredibly high temperature of 3,186 degrees Celsius / 5,767 Fahrenheit.
Let’s look at the various uses of rhenium and who produces it first in order to make an educated forecast on its future price (or click here to jump to the rhenium forecast).
Rhenium Uses
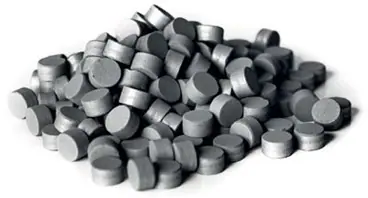
Rhenium’s remarkable properties make it indispensable across some of the world’s most advanced industries, from aerospace and defense to energy, electronics, and medicine.
Aerospace & Defense
Rhenium’s extreme heat resistance and tensile strength make it a key ingredient in the superalloys used for jet engine turbines, rocket nozzles, and combustion chambers. These nickel-based alloys typically contain up to 6% rhenium, which dramatically improves performance and durability at temperatures exceeding 1,000 °C. The metal is also used in tungsten-rhenium thermocouples, crucial for precise temperature measurements in high-performance engines.
Energy & Catalysis
Rhenium is a cornerstone of modern refining technology. When added to platinum catalysts, it enhances efficiency and longevity in oil refining and fuel-reforming processes, reducing energy consumption and emissions. It also contributes to next-generation combustion systems in both power plants and industrial gas turbines, helping to improve efficiency and lower environmental impact.
Electronics & Technology
Rhenium’s excellent conductivity and stability make it ideal for electrical contacts, filaments, and electrodes. It is used in mass spectrometers, X-ray tubes, and specialised high-temperature electronic components, where reliability under stress is essential.
Medical & Research Applications
In the medical field, rhenium is gaining ground as a radiotherapeutic isotope. Rhenium-186 and Rhenium-188 are used in targeted cancer treatments and radiolabeled compounds for tumor imaging. These innovations are expanding rhenium’s role from an industrial material to a life-saving medical resource.
Emerging & Future Uses
As research intensifies, new applications continue to emerge, from additive manufacturing (3D-printed superalloys) to advanced coatings and quantum technologies. With no viable substitutes and an expanding range of uses, rhenium’s strategic importance is expected to grow significantly in the coming decade.
Where is Rhenium Produced?
Rhenium is the rarest stable element in the Earth’s crust, occurring at well below one part per billion. It is never found in mineable concentrations of its own and must be recovered as a by-product, primarily during the processing of molybdenum concentrates from large porphyry copper deposits. These ores typically contain only 0.001% to 0.2% rhenium, which makes extraction technically demanding and economically sensitive.
Global primary production remains extremely limited. The backbone of supply comes from just a handful of countries:
Chile: by far the most important source, thanks to its enormous copper industry and associated molybdenum recovery.
United States: primarily from molybdenum operations in Arizona, Utah, and Colorado.
Kazakhstan, Poland, and China: smaller but still meaningful contributors to global refinery output.
In total, annual worldwide production is estimated at around 40–50 tonnes of newly recovered rhenium, with an additional 12–15 tonnes coming from recycling and catalyst recovery. Even when combined, the entire global market sits at only ~62 tonnes per year, meaning any disruption, whether from Chilean copper politics, refinery maintenance, or shifts in aerospace demand, can have an outsized effect on price and availability.
Because rhenium extraction depends on the economics of copper and molybdenum mining rather than its own supply-demand fundamentals, production cannot easily scale in response to rising demand. This structural constraint is one of the key reasons rhenium remains both strategically important and persistently scarce.
What Factors Determine the Price of Rhenium?
Rhenium’s price is shaped by a combination of extreme scarcity, inflexible supply, and high-intensity industrial demand. Because the market is so small, barely 62 tonnes of annual supply worldwide, even modest shifts in consumption can trigger outsized price movements.
Demand-Driven Volatility
Rhenium is essential in jet engines, rocket nozzles, gas turbines, catalysts, and other high-temperature systems where no substitute exists. When demand rises from aviation, aerospace, or energy technologies, the market feels it immediately. Large order cycles from aircraft manufacturers or refiners can push prices sharply higher.
Constrained Supply
Supply is inherently tight because rhenium is not mined directly. It is recovered only as a by-product of molybdenum production, which itself is tied to global copper mining. This means rhenium output cannot easily increase when demand rises; production is dictated by copper and molybdenum markets, not by rhenium’s own price signal.
The extraction and recovery process is technically complex and expensive, further limiting how much material can economically reach the market.
Limited Dependence on China
Unlike rare earths and many other strategic metals, the rhenium supply chain is not dominated by China. While China is among the top producers, its output is largely consumed domestically. For Western industries, the critical suppliers remain Chile, the United States, Kazakhstan, and Poland.
This makes rhenium one of the few critical metals not directly exposed to Chinese export restrictions, but it doesn’t make the market any less fragile. Its bottleneck is geological and metallurgical, not geopolitical.
Rhenium Price Forecast
Forecast last updated: .
At a glance
- SMI’s published rhenium price stands at $7,421.13/kg on October 12, 2026, up 55.89% year to date after rising 91.50% in 2025 on SMI’s published USD series. The advance has continued beyond Q1.
- Commercial aerospace demand remains the main support, with higher engine deliveries providing evidence beyond long-term aircraft forecasts.
- Primary supply remains tied to copper and molybdenum processing, but recycling and improved recovery provide meaningful sources of additional material.
- The outlook remains constructive, with greater caution after the price rise and no assumption that previous gains establish a floor.
What changed for Rhenium in 2026
Rhenium’s continued price increase has been accompanied by stronger engine production. In its July 2026 results, Safran reported 1,030 LEAP engine deliveries in the first half, up 41% year over year, and raised its full-year delivery-growth outlook to the high teens. That supports the superalloy demand environment, although engine growth does not translate one-for-one into rhenium consumption.
The supply picture also deserves a more complete assessment. The USGS rhenium statistics and 2026 summary estimates 2025 world primary production at approximately 81 tonnes. It also reports industry estimates of 20–25 tonnes of secondary production, excluding spent-catalyst material retained within closed-loop recycling. These are historical estimates, not a measured 2026 supply balance.
SMI’s current price is 198.53% above the start of 2025. Such a substantial repricing strengthens the incentive to recover more metal and makes entry price increasingly important.
What this means for Rhenium
Rhenium remains a small, specialised market where changes in buying behaviour can move prices sharply. Its by-product dependence restricts how quickly supply can respond, but does not make production fixed.
More copper or molybdenum output helps only where the feed contains recoverable rhenium and suitable processing equipment is available. Ore composition, roasting throughput, recovery efficiency, and refinery operating conditions all matter. Secondary supply can respond through manufacturing scrap and retired components, although collection and processing take time.
A useful operating example is Codelco’s June 2026 update, which described approximately five tonnes of annual rhenium production through Molyb, using material from its copper operations. This documents an existing supply route, rather than a newly commissioned five-tonne expansion.
The investment case therefore rests on industrial demand outpacing these supply responses. It should not depend on assuming that a permanently worsening shortage is inevitable.
Price drivers tilting upward
- Commercial aerospace demand remains the main long-term support. Rhenium’s role in high-temperature turbine superalloys ties demand to aircraft-engine production and replacement components.
- Primary supply remains slow to expand. Higher rhenium prices do not automatically bring new copper mines, rhenium-bearing concentrates, or recovery circuits into service.
- Strategic relevance remains elevated. Rhenium was included in the final 2025 U.S. critical minerals list. This supports attention to supply security, but a designation alone does not establish government purchases or a guaranteed price premium.
- Substitution remains difficult in demanding applications. Qualified turbine alloys cannot simply be changed whenever metal prices rise. Petrochemical catalysts provide another established demand source.
Potential headwinds to watch
- After such a sharp move, consolidation or a correction remains plausible. A slowdown in aircraft production or industrial activity could soften near-term buying, while inventory reductions could amplify a correction.
- Recycling is already part of supply. Higher prices can encourage additional recovery from superalloy scrap. Closed-loop catalyst recycling also reduces the need to replace all catalyst metal with newly produced rhenium.
- Expansion proposals need careful interpretation. Molymet’s January 2026 agreement with Maritime House Metals concerns evaluating a recycling joint venture using existing facilities. Potential North American expansion depends on feedstock and commercial viability; the announcement does not establish commissioned additional capacity.
- Material efficiency can improve. Lower-rhenium alloys, alternative materials where suitable, and longer component life can moderate demand growth. Substitution is application-specific rather than impossible.
6–12 month Rhenium forecast view
Bias: Constructively bullish with volatility
Rationale: Higher engine deliveries and slow primary supply adjustment support the near-term case. However, after a 55.89% year-to-date gain, further increases will require continued buying pressure. A meaningful pullback remains possible if procurement pauses or more recycled material becomes available.
12–24 month forecast view
Bias: Cautiously bullish
Rationale: Continued aircraft-engine production and established catalyst uses favour sustained industrial demand. The balance depends increasingly on copper-molybdenum feedstock, recovery investment, and recycling. Confirmed output and deliveries should carry more weight than proposed capacity or strategic-purchasing plans.
3–5 year forecast view
Bias: Constructively bullish, but cyclical
Rationale: Rhenium’s specialised performance and by-product supply support its long-term relevance. Over several years, recycling, improved recovery, and material-saving designs have more time to develop. Prices could remain elevated if aerospace consumption grows faster than supply, but there is no assured permanently higher price range.
Why physical Rhenium fits the Strategic Metals Invest playbook
Rhenium fits the Strategic Metals Invest playbook unusually well because it combines several of the qualities that matter most in this asset class: a small market, demanding industrial applications, and primary supply tied to copper and molybdenum processing.
Its role in high-performance turbine alloys connects physical ownership directly to aerospace demand. Recycling provides an important supply response, but expanding primary recovery depends on suitable feedstock and specialised processing capacity. That combination can create opportunities when industrial demand strengthens.
Because rhenium trades through specialist industrial channels, documented purity, proper storage, and chain of custody are central to its resale potential. For patient investors, it offers exposure to a distinctive industrial market, with returns still dependent on entry price, future demand, and resale conditions.
How to Buy Rhenium
With its high melting point and impressive mechanical properties, rhenium is a coveted material in many industries. To ensure they get the best quality available, major corporate buyers such as Boeing, Airbus, and NASA tend to rely on renowned metal dealers who are able to source industry-grade rhenium of 99.9% purity or higher.
By guaranteeing product provenance, these so-called ‘key intermediaries’ also make it possible for global companies to access hard-to-find rare earth elements quickly and safely – something not achievable by buying online through less reputable channels like Amazon or Alibaba.
Rhenium should only be purchased from trusted sources that can deliver certifiable levels of quality control; otherwise, the metal can only be liquidated to hobbyists. We’re the only globally licensed industry supplier offering private investors the option to purchase and safely store industry-grade rhenium. Hence any discerning investor who wants to own some and benefit from potential future price increases can do this safely with us.
Rhenium futures contracts are also traded on the Shanghai Metal Market (SMM).
How to Sell Rhenium
If you have some rhenium at home, you should be able to sell it to other hobbyists via online marketplaces like eBay, Alibaba, and Amazon. The price you get will depend on what they offer, but it won’t be anywhere near the market price.
When it comes to selling industrial-grade rhenium, buyers like Lockheed Martin, SpaceX, and Boeing require more than just a secure transaction. To ensure that only quality materials are circulated in their production processes, they source their supply from trustworthy suppliers who can present documentary evidence of how each metal has been managed since its production – known as the chain of custody. That’s why they don’t shop on eBay.
Our investors can be confident that the liquidation of their strategic metals to industry buyers is secure and swift, as we are such a trusted industry supplier.
1 This price is based on the latest available industry-partner price for Rhenium, dated Oct 12 2026. Prices may be carried forward until a newer market price becomes available. Currency conversions use the latest available ECB exchange rate.
Calculations on this page last updated Oct 14 2026.